 lobal Securities News

BUUU Group to Acquire Brightray Stake and Raise $60 Million
BUUU Group Limited announced a definitive agreement to acquire a majority stake in Brightray Science Inc. and raised over $60 million in private placements.
香港の株式、債券、規制に関する最新ニュースを毎日更新。
Silicon Motion Technology (NasdaqGS: SIMO) has scheduled its third quarter 2026 results for late October. The company, which describes itself as the global leader in NAND flash controllers, cites trade and supply chain pressures among its risks.
BUUU Group Limited announced a definitive agreement to acquire a majority stake in Brightray Science Inc. and raised over $60 million in private placements.
The Hong Kong-based company listed on NASDAQ has completed a registered direct offering of Class A ordinary shares and pre-funded warrants.
The Hong Kong financial printer said customers reached a record 550 as of June 30, 2026, while IPO filing submissions to HKEX rose 482% year over year.
The Hong Kong AI and robotics group said its Axonex unit will co-develop a commercial grade service robot, with about 1,000 units planned for the forthcoming year.
The Hong Kong staffing and senior care group reported over 42% year-over-year logistics revenue growth and a record HK$4.4 million monthly revenue in June 2026.
The Hong Kong security services provider said Nasdaq confirmed it meets the minimum bid price requirement, keeping its Class A shares listed after a share consolidation.
The Hong Kong logistics group said Nasdaq gave it until February 8, 2027 to lift its market value of listed securities back to US$35 million.
The Hong Kong wet trades subcontractor will issue 1,377,000 Class A shares for a 20% stake in Beta Beteiligungs und Besitz GmbH, valued at US$23,400,000 in full.
香港の証券先物条例第XIVA部は、業績に重大な変動が見込まれる場合、上場企業に対し所定の決算発表日を待たず、合理的に実行可能な限り速やかにインサイダー情報を開示するよう義務付けている。その仕組みを解説する。
発行から国際間決済まで、香港金融管理局が運営する中央資金市場ユニット(CMU)が域内の巨大な債券市場で資金と証券をどのように安全に交換しているかを解説する。
香港取引所の第18A章と第18C章は、従来の利益テストの代わりに時価総額の基準、研究開発の進捗、そして専門知識を持つ投資家による裏付けを用いることで、赤字段階のバイオテクノロジー企業や特定技術企業にメインボード上場の道を開き、投資家保護の仕組みも備えている。
香港上場企業の株主構成の変化において、30%は法的に重要な境界線である。本稿は香港の買収合併規則(テイクオーバー・コード)に基づき、この閾値を超えると買収者がすべての株主に対して全部買付けの申し出を行う義務を負う理由と、関連する適用除外の基本的な考え方を解説する。
香港証券取引所のコーラブル・ブル/ベア証券は、あらかじめ設定された価格に達した瞬間に強制的に取引が終了する。これは通常のワラントや上場オプションとは根本的に異なる仕組みだ。
本土の銀行間市場から香港のオフショア・プラットフォームまで、人民元建て債券は2つのまったく異なる規制体系に従っています。本稿は、パンダ債とディムサム債の本質的な違い、および香港でのオフショア機関による人民元債発行のメカニズムを説明します。
毎営業日の開場前、見えない日次クォータゲートが本土と香港の株式市場間の資本流動を決める。このメカニズムが実際にどう機能するか。
新規株が正式に上場される前、香港取引所のFINI決済スケジュールには配分結果の発表から取引開始までの一晩の空白がある。本稿はこの空白がどこから生じるか、そして公式な初日取引と構造的にどう異なるかを整理する。
香港でのIPO購入において、機関投資家と個人投資家が全く異なるチャネルをたどる理由を解説します。各パスに適用される配分比率、クローバック・メカニズム、公衆保有株式(パブリックフロート)要件を明らかにします。
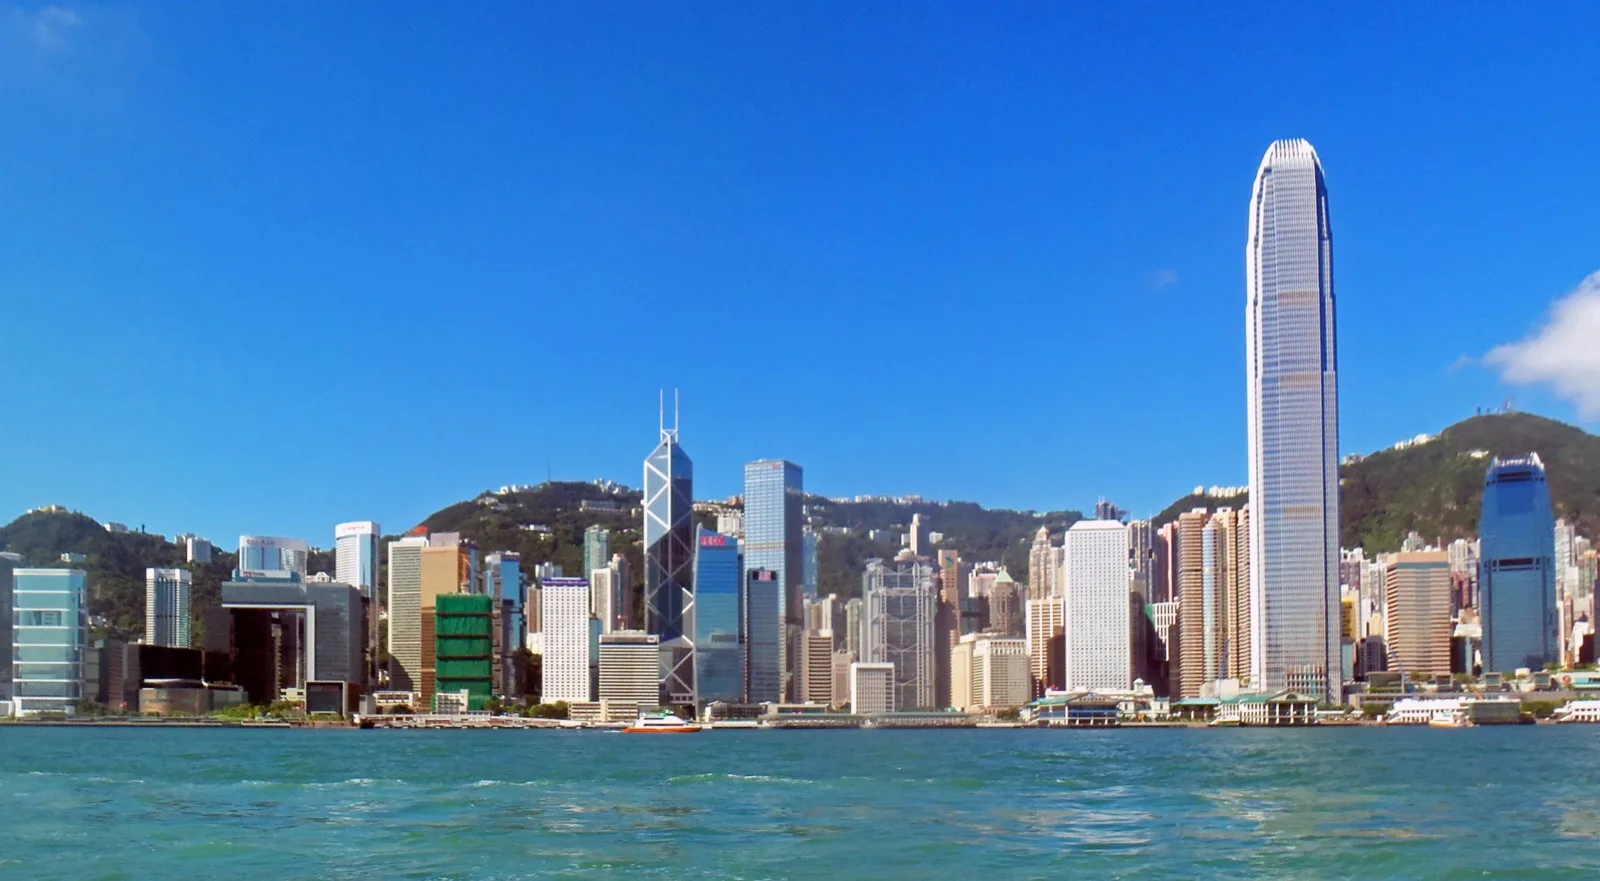
同一企業が異なる議決権を持つ2種類の株式を発行することができる理由と、香港取引所が創業者支配と少数株主保護のバランスを取るために設けた保護措置について。